
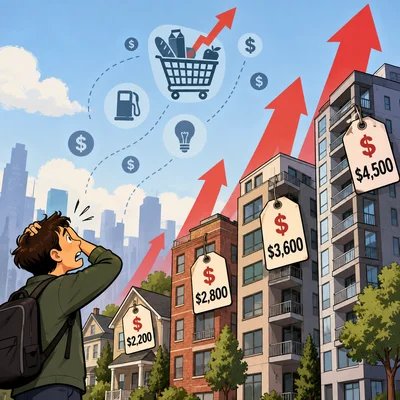
- Bank of England Deputy Governor Clare Lombardelli said policy is “increasingly likely to need to tighten” if elevated energy prices persist.
- She cited the Middle East conflict’s energy shock, strong AI-component demand, and weather-related shocks as upside inflation risks.
- Lombardelli stressed the Bank would not respond “mechanically” to energy price moves, focusing instead on how higher prices transmit through the economy.
- Her remarks came as US 30-year bond yields hit their highest level since 2004.
Bank of England Deputy Governor Clare Lombardelli has warned that UK interest rates are increasingly likely to rise if energy prices stay elevated, putting the prospect of further tightening back on the table even as the broader global bond market sells off. Speaking at the Sixth Biennial Conference on Macroeconomic Policy in Warsaw, Lombardelli said the energy shock stemming from the conflict in the Middle East is likely to keep pushing UK inflation higher in the coming months.
Her intervention lands at an awkward moment for markets. Long-dated government bonds have come under heavy pressure, with the US 30-year Treasury yield touching its highest level since 2004 — a move that reflects investors’ unease about persistent inflation, heavy government borrowing, and the risk that central banks keep policy restrictive for longer than previously assumed. UK gilts, sterling, and rate-sensitive sectors of the FTSE have all been caught up in the repricing.
The Transmission Problem, Not the Spot Price
Lombardelli was careful to frame the issue as one of transmission rather than the headline price of oil or gas. “The key issue is not the spot price of energy itself but the interaction of the underlying economy, higher energy prices, and the nature of their transmission,” she said, adding that the Bank is “by no means suggesting that monetary policy should respond mechanically to movements in energy prices.”
That distinction matters for how markets read the Bank’s reaction function. A purely mechanical response to an energy spike would risk overtightening into a slowdown; ignoring it entirely risks allowing a temporary price shock to become embedded in wages and pricing. Lombardelli’s point is that the longer elevated energy costs persist, the greater the risk that indirect effects build and that inflation expectations, wage bargaining, and price-setting behaviour begin to adjust in response.
Competing Forces on UK Inflation
She also flagged forces pulling in the opposite direction. Strong demand for AI components is already pushing up global export prices, and weather-related shocks add further upside risks to inflation. On the other side of the ledger, trade diversion — the redirection of goods flows as tariffs and geopolitical fragmentation reshape supply chains — is acting to reduce inflation.
The net effect is a UK inflation outlook that depends heavily on how long the energy shock lasts and how forcefully it feeds into domestic costs. Lombardelli’s conclusion was conditional rather than prescriptive: policy is increasingly likely to need to tighten if elevated energy prices persist, absent clear evidence of disinflation or weaker activity.
What It Means for Rates and Markets
For investors, the message is that the Bank’s easing path — if one exists — is not guaranteed. Sterling has been sensitive to rate differentials, and a hawkish shift in Bank of England expectations would typically support the pound while weighing on gilt prices. UK domestically focused equities, particularly consumer-facing names exposed to mortgage costs and household budgets, are the most directly exposed to any change in the rate outlook.
The global backdrop complicates the picture further. With US long-bond yields at multi-decade highs, the cost of capital is rising across developed markets, and any economy carrying persistent inflation risks faces a harder trade-off between supporting growth and anchoring expectations. Lombardelli’s remarks suggest the Bank of England is not yet prepared to declare victory on inflation, and that the energy channel remains the single largest source of uncertainty in the UK outlook.

Comments are closed.