
- Asian equity benchmarks traded mixed, with no single regional direction dominating the session.
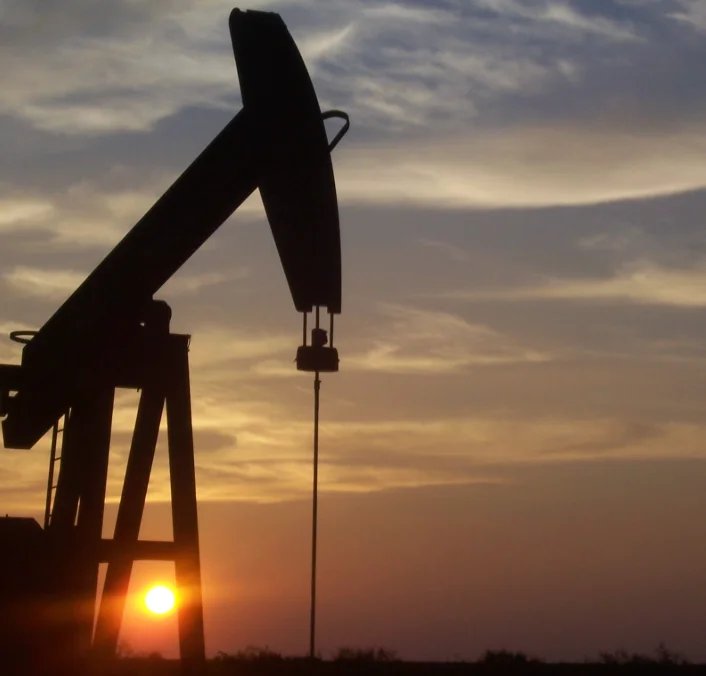
- Rising oil prices were a central theme, lifting energy-linked assets while pressuring import-dependent economies.
- Crude strength feeds directly into headline inflation through fuel and freight costs, complicating the rate outlook for major central banks.
- Investors continue to weigh energy-driven inflation risk against the growth outlook for export-heavy Asian economies.
Asian equity markets finished mixed as crude oil prices moved higher, leaving investors to reconcile a supportive backdrop for energy producers with the cost pressure that costlier crude places on the region’s import-dependent economies. The split session reflected that tension rather than a single dominant narrative, with some benchmarks advancing while others slipped. Energy shares generally found support from the move in oil, while transport, airline, and chemical names — whose margins are sensitive to fuel and feedstock costs — faced headwinds.
Why Oil Is the Swing Factor
Oil sits at the center of the current macro debate because it transmits into inflation through multiple channels at once. Higher crude raises pump prices, jet fuel and diesel costs, and the freight expense embedded in nearly every imported good. For Asian economies that import the bulk of their energy needs, that pass-through shows up in trade balances as well as consumer price indexes. Japan, South Korea, India, and much of Southeast Asia are structurally exposed to crude import costs, which means a sustained rise in oil can widen deficits and weaken currencies at the same time it lifts inflation.
That combination is awkward for central banks. If headline inflation accelerates because of energy rather than domestic demand, policymakers face a choice between tightening into a slowdown or looking through the move and risking an inflation-expectations problem. The US Federal Reserve, the European Central Bank, and the Bank of Japan have all had to navigate energy shocks in recent years, and the playbook is rarely clean. A purely supply-driven oil move tends to act like a tax on growth: it raises costs without adding demand, which is precisely why equity markets often struggle to hold gains when crude climbs sharply.
What It Means for Portfolios
For investors, the practical implication is a rotation rather than a uniform risk-on or risk-off signal. Integrated oil majors, exploration and production companies, and oil services firms typically see earnings estimates revised higher when crude rallies, and energy has historically been one of the few sectors that can outperform during inflationary episodes. Broad market index exposure, by contrast, becomes more dependent on whether companies can pass input costs through to customers. Airlines and logistics operators are among the most directly exposed to fuel prices, while consumer discretionary names face pressure if higher fuel bills eat into household budgets.
Watch the Currency Channel
Currency markets often amplify the equity signal. Oil is priced in dollars, so a stronger dollar makes crude more expensive for buyers using other currencies, adding a second layer of cost for Asian importers. When local currencies weaken against the dollar, the effective price of imported energy rises even if the dollar-denominated benchmark is unchanged. That dynamic can force central banks into defensive rate moves, which in turn pressures equity valuations. Traders watching this story should track the dollar index alongside crude benchmarks, since the two together determine the real cost burden on importing economies.
Looking ahead, the direction of oil prices will likely remain the dominant variable for Asian equities. A sustained move higher would keep energy stocks bid but weigh on the broader index through inflation and margin pressure, while a reversal would relieve cost pressure and potentially broaden market participation. For now, the mixed session is a reasonable reflection of genuine uncertainty: markets are not treating higher oil as unambiguously good or bad, but as a force that redistributes returns across sectors and regions. Investors should expect that dispersion to continue until the path of crude becomes clearer.

Comments are closed.