
- Asian equity benchmarks traded mixed, with no single direction dominating regional markets.
- The session followed a global bond sell-off that pushed sovereign yields higher across major markets.
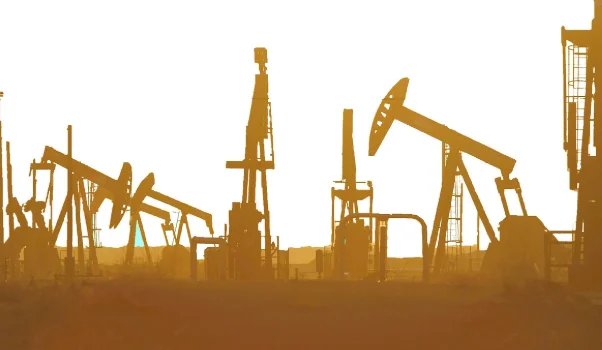
- Oil prices dropped, weighing on energy-linked equities while easing input-cost pressure elsewhere.
- Higher bond yields typically pressure growth and technology valuations, while lower crude cuts costs for transport, airlines and chemicals.
- Currency and rate-sensitive sectors remained the main swing factors for regional indexes.
Asian shares finished mixed on the session, with regional benchmarks splitting between modest gains and declines as investors worked through the aftermath of a global bond sell-off and a sharp drop in oil prices. The two forces pulled in opposite directions: rising sovereign yields raise the discount rate applied to future corporate earnings and tend to hit long-duration growth stocks hardest, while cheaper crude lowers operating costs for large parts of the industrial and consumer economy. The net result was a market without a clear directional bias, where sector rotation mattered more than the headline index level.
Bonds Set the Tone
The bond market was the dominant driver. A broad sell-off in government debt pushed yields higher across major markets, a move that tightens financial conditions without any central bank having to act. When yields rise quickly, equity investors reprice the risk-free alternative, and the effect is rarely uniform. Companies whose valuations depend on profits far in the future — technology, biotechnology and other growth names — typically see the sharpest multiple compression, while banks and insurers can benefit as lending margins and reinvestment yields improve. That split helps explain why regional indexes diverged rather than moving as one block.
For Asian exporters and manufacturers, the yield backdrop also matters through the currency channel. Higher US yields have historically supported the dollar, which can weigh on Asian currencies and, by extension, on the translated value of overseas earnings. A stronger dollar also makes dollar-denominated commodity imports more expensive for regional buyers, a consideration that partially offsets the benefit of cheaper energy.
Oil’s Slide Cuts Both Ways
The drop in crude prices was the second defining feature of the session. Falling oil is unambiguously good news for energy importers, and much of Asia sits firmly in that category. Lower fuel costs feed through to transport, logistics, airlines, chemicals and consumer discretionary spending, effectively acting as a modest tax cut for households and businesses. In economies where fuel subsidies or administered pricing exist, the pass-through can be slower, but the direction of pressure on inflation is still downward.
Winners and Losers
The flip side is the energy complex itself. Oil producers, refiners and oilfield services companies see revenue and margin expectations trimmed when crude falls, and energy-heavy indexes in the region underperform accordingly. The tension between cheaper input costs for the broad economy and weaker earnings for energy names is one reason the overall market struggled to find a consistent direction.
Looking ahead, the near-term path for Asian equities likely depends on whether the bond sell-off stabilizes or extends. A calmer rates market would remove the single biggest source of valuation pressure and allow the disinflationary benefit of lower oil to show up more clearly in earnings expectations. A further leg higher in yields, by contrast, would keep growth sectors under pressure and reinforce the preference for cash-generative, dividend-paying businesses. Investors should also watch currency moves, since a sustained dollar advance would complicate the picture for exporters even as energy costs fall. For now, the market’s message is one of rotation rather than retreat — a session defined less by where indexes closed than by which sectors carried them there.

Comments are closed.