
- Lam Research is scheduled to report quarterly results, with the company’s fiscal first-quarter 2026 earnings release and conference call expected after the market close.
- Wall Street’s focus centers on wafer fabrication equipment (WFE) spending trends, China revenue mix, and management’s outlook for the December quarter.
- Lam is a bellwether for the semiconductor capital equipment group, alongside peers Applied Materials and KLA.
- Key swing factors include NAND and DRAM customer capital spending, advanced packaging demand tied to AI accelerators, and export-control developments.
- Options markets typically price an outsized single-day move in LRCX shares around the print.
Lam Research ($LRCX) is one of the most closely watched names in the semiconductor supply chain, and its quarterly report lands at a moment when investors are trying to gauge whether the artificial intelligence buildout is translating into durable demand for wafer fabrication equipment. Lam’s tools perform deposition and etch steps — critical processes for making both leading-edge logic chips and high-density memory. That makes the company’s order book a useful proxy for how aggressively chipmakers are expanding capacity.
What the Numbers Will Say
Analysts typically frame Lam’s results around three lines: revenue, gross margin, and guidance for the coming quarter. The systems revenue segment reflects tool shipments to foundry, logic, and memory customers, while the customer support business provides a steadier, higher-margin revenue stream that has grown in importance as the installed base expands. Gross margin trends matter because product mix — particularly the share of revenue from leading-edge deposition and etch platforms — can swing profitability meaningfully from quarter to quarter.
Guidance will likely carry more weight than the reported quarter itself. Management’s commentary on the December quarter sets expectations for the entire WFE sector, and any revision to the company’s view on calendar-year spending will ripple across peers. Investors will also parse the deferred revenue balance and backlog disclosures for signs of order momentum heading into 2027.
China, Memory, and the AI Variable
China remains the single biggest swing factor for Lam and its competitors. Export controls imposed by the U.S. government have repeatedly reshaped the company’s revenue mix, and any change in licensing policy or entity-list designations can shift the outlook with little warning. Lam has consistently disclosed the revenue contribution from China in its filings, and that figure will be scrutinized for evidence of either normalization or renewed volatility.
Memory is the second key variable. NAND and DRAM makers cut capital spending sharply during the last downturn, and the question now is how much of that spending returns. AI servers have driven strong demand for high-bandwidth memory, which requires advanced packaging and additional deposition steps — a tailwind for Lam’s product portfolio. If memory customers signal a broader equipment upgrade cycle, Lam stands to benefit disproportionately given its etch and deposition leadership.
Valuation and Positioning
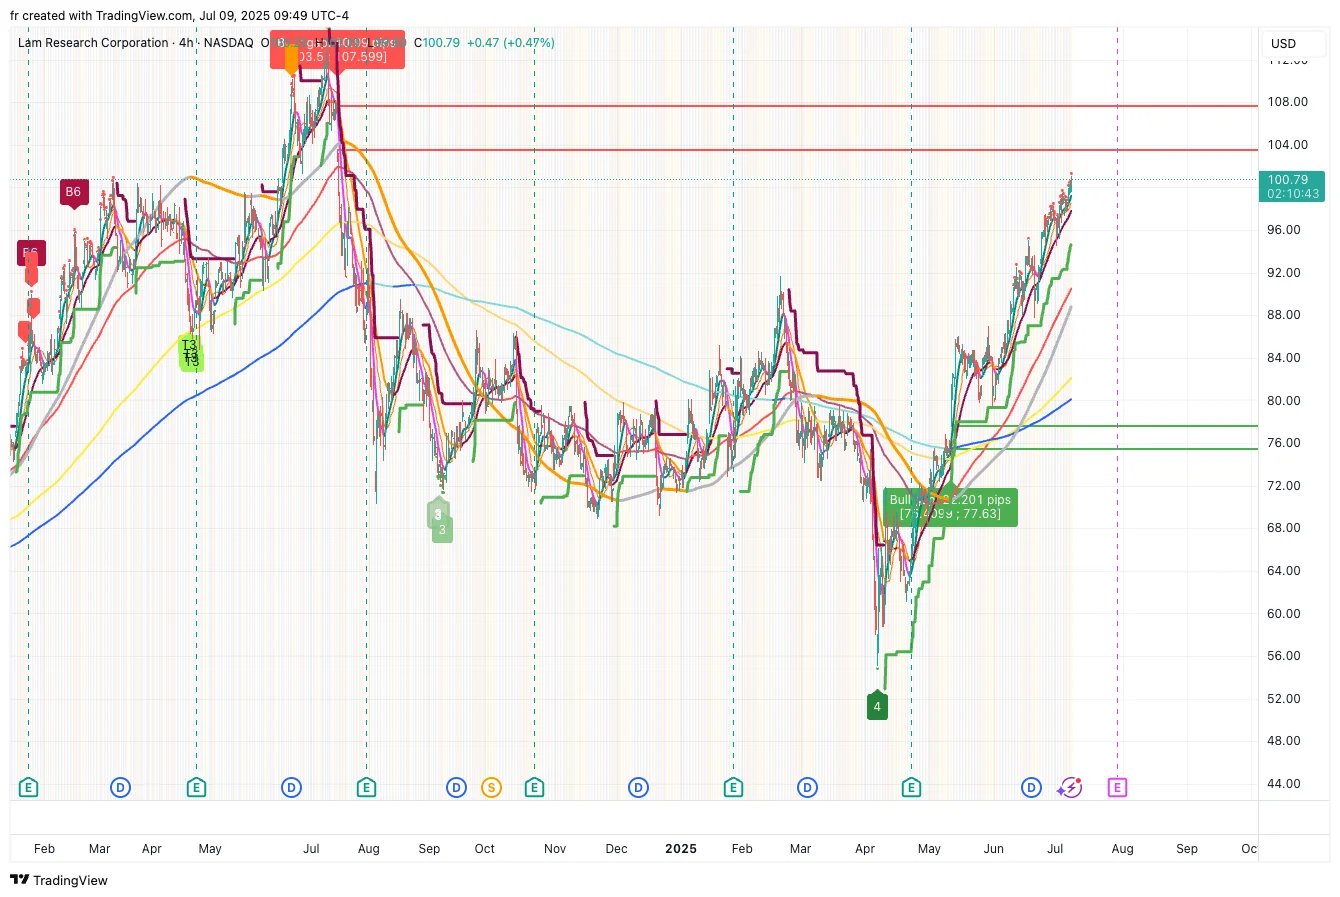
Lam shares have historically traded at a premium to the broader market, reflecting the company’s strong free cash flow generation and consistent capital returns through buybacks and dividends. That premium compresses and expands with the WFE cycle. Heading into the print, positioning matters: if investors have already priced in a strong beat-and-raise, the bar for a positive stock reaction is higher, and even solid results can trigger profit-taking.
For the broader market, Lam’s report functions as an early read on the health of semiconductor capital spending. Applied Materials ($AMAT) and KLA ($KLAC) typically trade in sympathy with Lam’s results and guidance, and the read-through extends to chipmakers themselves. A confident outlook would reinforce the narrative that AI infrastructure spending remains intact; a cautious one would raise questions about the pace of capacity additions into 2027. Either way, the reaction in LRCX shares and the equipment group will be the clearest signal of what investors take away from the report.
Source: barchart.com