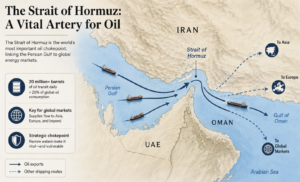
- US equities fell as Brent crude surged 5.37% to $105.58 and Treasury yields stayed elevated, reviving inflation worries.
- Technology megacaps Amazon, Tesla, and Nvidia led the decline, dragging the broader tech sector lower.
- Investors are turning attention to the approaching third-quarter earnings season, with financial institutions first to report.
- The Federal Reserve is widely expected to hold rates steady at its October meeting while keeping future hikes on the table.
The selling was broad but concentrated in technology, where the market’s largest and most rate-sensitive names absorbed the heaviest losses. Amazon, Tesla, and Nvidia all traded lower, and their declines weighed on the major indexes given their outsized index weights. When the biggest growth names fall together, the drag on cap-weighted benchmarks such as the S&P 500 and Nasdaq-100 is magnified, and the weakness tends to spill into adjacent sectors as sentiment sours.
Yields and Oil Squeeze Valuations
The combination of elevated yields and a fresh leg higher in crude is the core of the current market anxiety. Higher yields raise the cost of capital for businesses and households alike, while oil near $105 per barrel feeds directly into transportation, manufacturing, and consumer energy costs. For equity investors, that mix threatens the disinflation narrative that supported the rally through much of the year. If energy-driven price pressure persists, it could keep the Federal Reserve cautious even as other inflation measures cool.
Energy is the obvious relative beneficiary of the move, with integrated majors and oilfield services names typically outperforming when crude spikes. The pain is more diffuse: airlines and trucking companies face higher fuel bills, retailers confront squeezed consumer budgets, and rate-sensitive sectors such as real estate and utilities struggle when yields stay high. That rotation dynamic helps explain why the headline indexes can fall even when one large sector is rallying.
Earnings Season Takes Center Stage
With macro headlines dominating, investors are increasingly focused on the approaching third-quarter earnings season, particularly the early reports from financial institutions. Banks are typically first to report and their results offer an early read on credit conditions, net interest margins, and loan demand. Commentary from management on consumer health and borrowing costs may matter more than the headline numbers themselves, given how much of the current market debate hinges on whether higher rates are finally biting.
On monetary policy, the Federal Reserve is expected to keep interest rates unchanged at its October meeting while leaving the door open to future moves. That stance reflects a central bank still weighing sticky inflation against signs of cooling in parts of the economy. For equity markets, the path of least resistance likely depends on whether oil retreats and yields stabilize. Until then, volatility in megacap technology and energy-led inflation headlines are likely to keep driving the daily tape.
Source: economictimes.indiatimes.com